Why You Need This Checklist
What if crossing a single dollar threshold cost you over $2,200 this year — and you had no idea it was coming? That is exactly how IRMAA works, and most people approaching Medicare have never heard of it until the bill arrives.
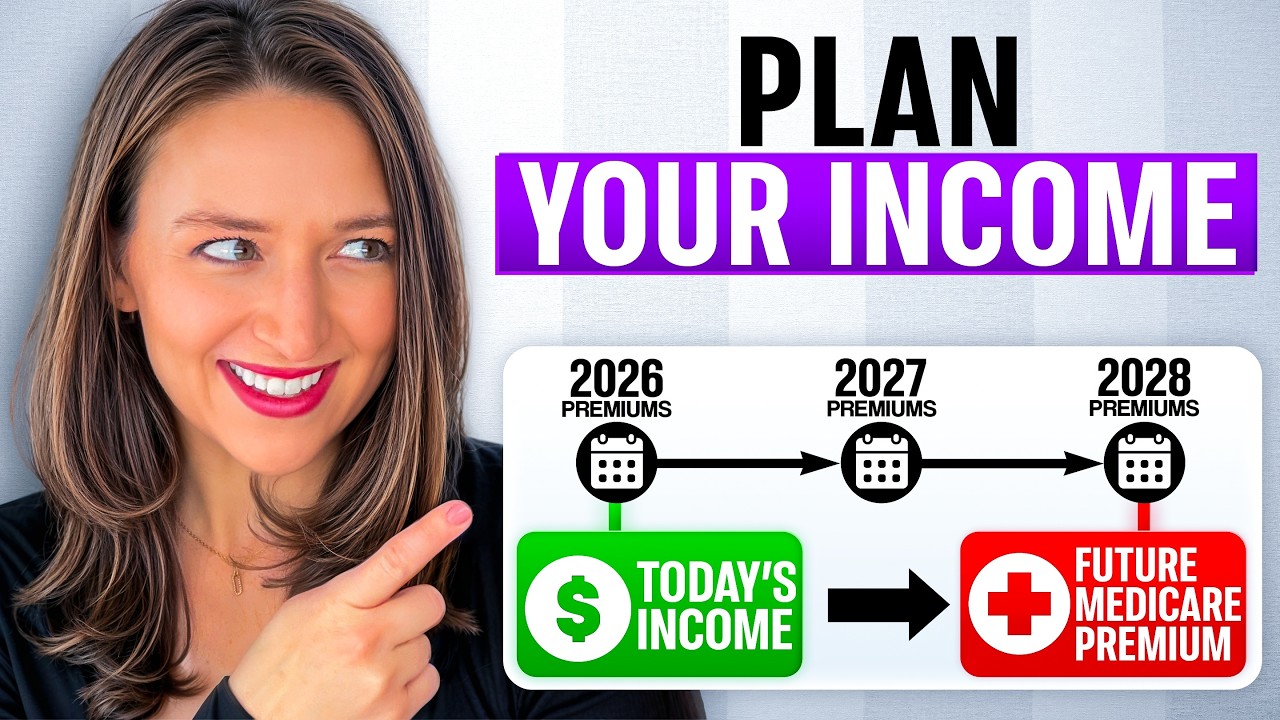
IRMAA, the Income-Related Monthly Adjustment Amount, is a surcharge added to your Medicare Part B and Part D premiums if your income exceeds certain thresholds. And unlike a regular tax bracket, it is a cliff. Cross the line by even $1 and you owe the full surcharge for the entire year. For a married couple, that first cliff alone can cost over $2,200 annually. At the highest income tier, surcharges can reach nearly $9,400 per person per year. The worst part? Medicare looks back two full years to calculate what you owe today, meaning decisions you made in 2024 are showing up in your 2026 premiums right now.
Imagine heading into retirement with a clear, confident plan. You know exactly how to calculate your Modified Adjusted Gross Income for IRMAA purposes. You know how to build in a smart buffer so a surprise dividend or capital gain does not accidentally push you into the next tier. You know when it actually makes sense to intentionally pay an IRMAA surcharge because doing so protects you from far larger RMD tax bills down the road. That kind of clarity is worth thousands of dollars over the course of your retirement.
Erin Moriarity of Erin Talks Money has built a reputation for breaking down exactly these kinds of complex retirement planning topics in a way that is honest, practical, and immediately usable. Her breakdown of IRMAA — including the two-year look-back, the bracket cliff mechanics, and the three distinct planning approaches real advisors use — is one of the most thorough explanations available for everyday retirees and pre-retirees.
This checklist distills everything from that video into a clear, step-by-step action plan you can apply to your own situation today. From calculating your MAGI correctly (yes, municipal bond interest counts) to forecasting future brackets, building income buffers, and deciding whether intentional IRMAA acceptance might actually save you money long-term, every key step is laid out in plain language. Pick it up, work through it at your own pace, and stop leaving thousands of dollars on the table due to planning gaps you did not know existed.
What's Inside — Preview
Every checklist item comes with actionable notes to guide you — things like "Don't forget to do this before you start," "Avoid this common mistake," or "Set a reminder for 30 days out." Nothing vague, just clear next steps.
LEARN
Understand what IRMAA is and confirm whether it applies to you
LEARN
Memorize the cliff mechanic — IRMAA is all-or-nothing, not graduated
LEARN
Learn the 2026 IRMAA tiers for Part B and Part D
LEARN
Understand the two-year look-back rule and which tax year affects your current premiums
LEARN
Acknowledge that IRMAA thresholds shift every year due to inflation indexing
+ 15 more action items inside...
 ▶ Watch the source video on YouTube